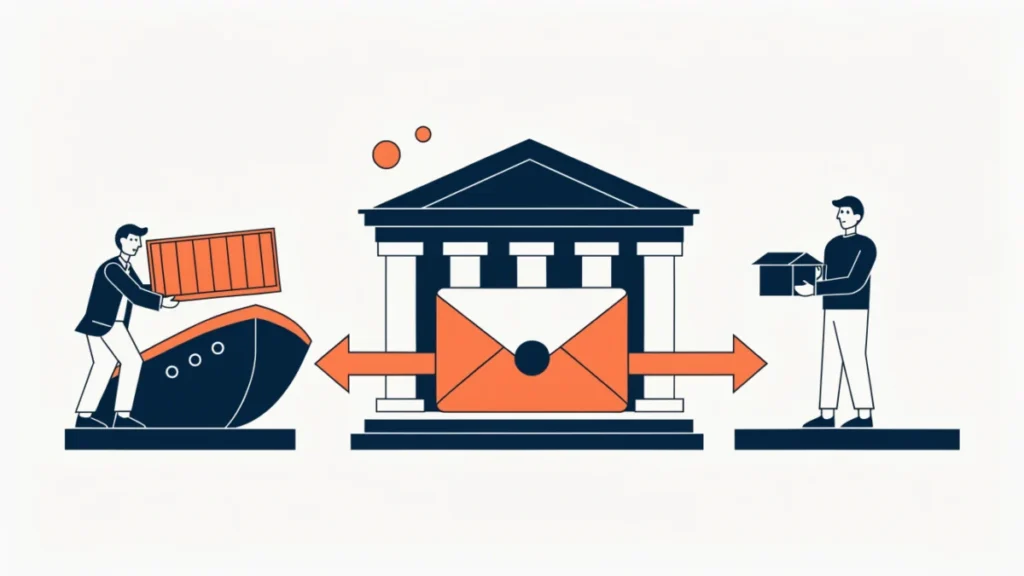
A letter of credit (LC) is a bank’s promise to pay the exporter once documents matching the LC terms are presented, which removes most payment risk between buyers and sellers who do not know each other. Most LCs follow the ICC’s UCP 600 rules. The trade-offs are bank fees, heavy and strict documentation, slow processing, dependence on banks, and the risk that a small document discrepancy delays or blocks payment.
In international trade, where goods and services cross borders, diverse currencies are exchanged, and unfamiliar parties engage in transactions, trust and security become top. It’s in this intricate dance of global commerce that Letters of Credit (LCs), often hailed as the lifeblood of international trade, emerge as invaluable instruments. They serve as the bedrock upon which multinational deals are struck, promising payment assurance and risk mitigation to both buyers and sellers.
What is a Letter of Credit?
A Letter of Credit, often referred to as a documentary credit, serves as a financial contract that bridges the gap between buyers and sellers engaged in cross-border transactions. It is a promise, etched in the ink of trust, issued by a bank on behalf of a buyer to guarantee payment to a seller, provided that the seller fulfills specific terms and conditions carefully outlined in the LC.
This financial guardian matters a lot in building global trade by mitigating risks, establishing standards, and facilitating transactions that span across borders and currencies.
Here’s a brief overview of the key components and parties involved in a typical LC transaction:
- Applicant: The buyer or importer who requests the issuance of the LC from their bank.
- Beneficiary: The seller or exporter who will receive payment under the LC upon fulfilling its terms and conditions.
- Issuing Bank: The bank chosen by the applicant to issue the LC.
- Advising Bank: The bank located in the beneficiary’s country, is responsible for advising the LC to the beneficiary.
- Confirming Bank (optional): In some cases, the LC may be confirmed by another bank to provide additional assurance to the beneficiary.
- Terms and Conditions: The LC outlines specific requirements that the beneficiary must fulfill, such as presenting shipping documents, complying with quality standards, or meeting delivery deadlines.
Advantages of Letters of Credit
1. Risk Mitigation
Letters of Credit are a powerful tool for risk mitigation because they establish a clear set of conditions that must be met before payment is made.
Read more: Advantages and disadvantages of commercial banks.
Read more: Advantages and disadvantages of export finance.
This reduces the risk of fraud, non-delivery, or other breaches of contract. For example, if a seller ships goods that do not conform to the agreed-upon specifications, the buyer can reject the documents, and payment will not be made until the issue is resolved.
2. International Acceptance
The widespread acceptance of LCs in global trade means that they are recognized and trusted by businesses and banks worldwide.
This universality makes LCs an attractive choice for parties engaged in cross-border transactions, as they provide a standardized and reliable method for conducting international business.
3. Creditworthiness
In international trade, buyers and sellers often have limited knowledge of each other’s financial stability. By relying on the issuing bank’s creditworthiness, LCs provide an extra layer of assurance. This is particularly valuable when dealing with new or unknown trading partners.
4. Flexible Payment Terms
LCs offer flexibility in negotiating payment terms. Buyers can work with sellers to determine payment upon delivery, after inspection, or on a deferred basis.
This flexibility enables parties to structure the transaction in a way that aligns with their cash flow and financial objectives.
5. Currency Flexibility
LCs can be issued in various currencies, allowing parties to choose the currency that best suits their needs. This feature reduces the risks associated with exchange rate fluctuations and simplifies the process of conducting transactions in multiple currencies.
6. Documentary Control
The requirement for specific documents under LCs ensures that both parties are accountable for their obligations.
Sellers must provide accurate and complete documentation, while buyers must carefully review the documents to verify compliance with the terms and conditions of the LC.
7. Trade Financing
LCs can serve as a source of trade financing for buyers. Banks may offer financing options, such as issuing a letter of credit with a deferred payment date, enabling buyers to effectively manage their working capital.
8. Legal Protection
LCs provide a well-defined legal framework for international trade disputes. In the event of a dispute, the parties can refer to the terms and conditions outlined in the LC.
This can simplify the resolution process and reduce the likelihood of protracted legal battles.
9. Wide Applicability
Letters of Credit are not limited to specific industries or types of products. They can be used in a wide range of sectors, from manufacturing to agriculture to services, making them a versatile tool for businesses across various sectors.
10. Improved Cash Flow
For sellers, LCs provide a predictable payment schedule. This predictability can be important for managing cash flow and planning for future business activities, as it allows sellers to anticipate when funds will be received.
11. Strengthened Supplier Relationships
The use of LCs can build trust and confidence between buyers and sellers. Knowing that payment is secured upon compliance with the LC terms encourages the development of long-term supplier relationships based on mutual trust and reliability.
12. Customization
LCs can be customized to suit the unique needs of a transaction. Parties have the flexibility to specify terms, conditions, and requirements that are tailored to their particular trade arrangement, providing a level of control over the transaction’s details.
13. Regulatory Compliance
LCs often help parties comply with import and export regulations, including documentation requirements, customs procedures, and trade restrictions. This ensures that the transaction adheres to all applicable laws and regulations, reducing the risk of legal issues.
Disadvantages of Letters of Credit (LCs)
1. Complex Documentation
LC transactions involve an extensive amount of documentation, including invoices, bills of lading, certificates of origin, inspection certificates, and more.
Managing and verifying this documentation can be a complex and time-consuming process, requiring careful attention to detail.
2. Costs
LCs can be costly for businesses. Banks charge fees for issuing, confirming, and advising LCs. These fees can add up, particularly for small and medium-sized enterprises (SMEs), impacting the overall cost of the transaction.
3. Risk of Non-Payment
While LCs provide security against certain risks, there is still a risk of non-payment for sellers.
If discrepancies arise in the documents, or if the buyer disputes the quality or quantity of the goods, payment can be delayed or even withheld, causing financial losses for the seller.
4. Limited Flexibility
LCs are often rigid in their terms and conditions. Once established, they can be challenging to modify or amend. This lack of flexibility can be problematic when unexpected changes or issues arise during the course of the transaction.
5. Time-Consuming Process
LC transactions can be time-consuming, especially when discrepancies or disputes arise.
Resolving these issues may require back-and-forth communication between the parties and the banks, leading to delays in payment and delivery.
6. Dependence on Banks
LC transactions rely heavily on banks, which can introduce a level of dependency and potential delays. Any errors or inefficiencies on the part of the banks involved can impact the smooth execution of the transaction.
7. Risk of Fraud
While LCs are designed to provide security, they are not immune to fraudulent activities.

Fraudulent documents, such as counterfeit bills of lading or certificates of origin, can still be presented, potentially leading to financial losses for the parties involved.
8. Currency Exchange Risk
While LCs can be denominated in various currencies, they may still expose parties to currency exchange risk if significant fluctuations occur between the time of LC issuance and payment. This risk can affect the profitability of the transaction.
9. Confidentiality
LCs are financial instruments, and the details of the transaction may be known to multiple parties, including banks, intermediaries, and potential competitors.
This can impact the confidentiality of the deal and may be a concern for businesses with sensitive trade information.
How a Letter of Credit Works:
- LC Issuance: The buyer (applicant) approaches their bank (issuing bank) and requests the issuance of an LC in favor of the seller (beneficiary). The buyer provides the bank with the necessary details, including the terms and conditions of the LC, the amount to be paid, and the beneficiary’s information.
- LC Transmission: The issuing bank sends the LC to an advising bank in the beneficiary’s country. The advising bank notifies the beneficiary of the LC’s existence and terms.
- Shipment and Compliance: The seller prepares the goods and arranges for their shipment in accordance with the LC’s terms and conditions. This includes ensuring that all required documents are obtained and correctly prepared.
- Document Presentation: Once the shipment is made, the seller presents the required documents, such as invoices, bills of lading, certificates of origin, and inspection certificates, to either the advising bank or the confirming bank (if applicable).
- Document Examination: The bank (advising or confirming) carefully examines the presented documents to ensure they comply with the LC’s requirements. If there are any discrepancies or missing documents, the bank may request corrections or additional information from the seller.
- Payment or Rejection: If the documents are in order and comply with the LC’s terms, the bank makes payment to the seller as specified in the LC. If there are discrepancies, the bank may reject the documents, leading to a negotiation process between the buyer and seller to resolve the issues.
- Closure: Once payment is made or discrepancies are resolved, the LC is considered fulfilled and closed.
Conclusion:
In the world of international trade, letters of credit matters a lot in facilitating secure and trustworthy transactions. Understanding the advantages and disadvantages of LCs is important for businesses and individuals engaged in cross-border commerce.
While LCs offer protection, financial security, and a framework for international transactions, they also come with complexities, costs, and potential risks.
Careful consideration of these factors and expert guidance can help parties use the benefits of LCs while mitigating their drawbacks. Ultimately, a well-informed approach to letters of credit can contribute to successful global trade endeavors.